


If you already maintain an active portfolio, advisory relationship or trading account with one of our Group Companies, please reach out to your usual contact or otherwise via email on info@axis-im.com, for a full access code to all sections in this Newsletter, inclusive of (i) Pay-Walled content on Specific trade recommendations, (ii) Entry and Exit timings and (iii) Risk Management Parameters.
Access Codes also available for Trusted Media contacts.
For more information on what we do and the services we offer, please visit www.axis-im.com.
CIO Travel Plans & Investor Meetings
Upcoming CIO Visits are below. Please reach out if any of these destinations pique your interest:-
Dubai & Abu Dhabi, UAE : 26th - 29th October ; Singapore : 30th October ; Lisbon, Portugal : 12th - 15th November ; Malaga, Spain : 16th November
CIO Occasional Commentary
The game in town seems to be picking the level where US 10 Year Yields (might) sink the overall Stock Market. 5% Yields didn’t do it, when it was widely feared that all would end once we broke through that level. Historic data is informative but far from conclusive, especially as the long run studies incorporate 1930s/40s/50s depressions, wars, repressions and deflation concerns. Today’s businesses are different with Indices composed of asset-light businesses in technology. Profit margins are also incomparable, compounded by changes in accounting standards and buybacks.
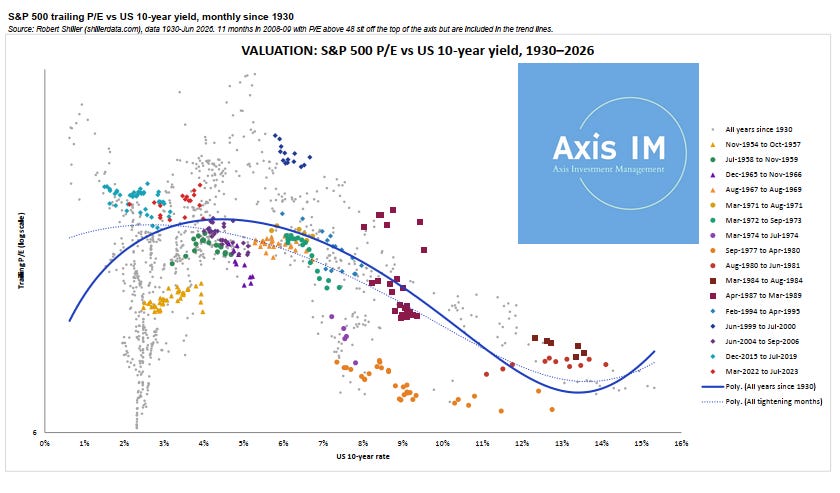
The above (e&oe) illustrates how the Price/Earnings Ratio of the S&P 500 Index has performed in a wide range of interest rate environments. Each Dot is a single monthly reading.
The smoothed line indicates that we are in a relatively benign zone currently, at ~5% rates, in the context of wider history (ironic given every panicked news headline..). Optimists can take from this that these conditions can certainly be absorbed by the broad market (which seems to have been the case, thus far). Whilst those who are more cautious can argue that valuations are pricing in perfection and there is no cushion in the event of a yield spike or any growth stumble. The declining line (left to right) suggests that growth and performance is dampened once Yields surpass ~5.5% - but we would not consider this to be a reliable timing or forecasting tool, in isolation.
Instead, we continue to use these studies alongside our own proprietary technical, valuation and momentum tools, in conjunction with derivatives and option markets analytics, to inform our strategy.
We are mindful that any of
(i) A Yield Spike
(ii) Any GDP or PMI disappointment
(iii) Worsening Geopolitics (can it even get any worse or more inhumane than it is already) or
(iv) A grindingly slow, unrelenting and painful melt-up in yields
can derail this market or present a material correction.
Hence, we are adopting the below toolkit - covering Credit, Debt and FX, to stay out of harm’s way without having to forfeit market upside:-
(For Asset Class Allocation percentages, inclusive of Real Estate, please contact us)
Credit
Increased Vigilance on Credit Quality.
Minimum S&P Rating at 2 notches below Investment Grade. 2 Ratings Agencies from S&P, Moody’s or Fitch preferred.
Duration limited to 5 years maximum with a sweet spot at 3 Years. Exceptions subject to High Investment Grade Credit Ratings.
USD and GBP credit currencies.
Limited EUR credit exposure.
Avoidance of BDC, SASB or similarly concentrated assets
(for our preferred issuers and sectors, please reach out to your Axis IM Contact)
Equities (an illustrative truncated list of our proprietary 50+ criteria metrics)
Total Leverage limited to 35%
High Liquidity Listing Venues
>3 Year Order Book visibility at stock or sector level
Forward PEG below 1.25
Forward Dividend Coverage (where applicable) over 125%
Proprietary Technical and Momentum Studies presenting as Neutral or higher
Sector and ETF bias, with limited precise exposure to individual names
(for our preferred issuers, equity names and sectors, please reach out to your Axis IM Contact)
Covered Calls where appropriate
FX / Commodities / Shorter Term Trades (tactical)
If you would like to view the Investment Recommendations Section below, please request access from your Axis point of contact.